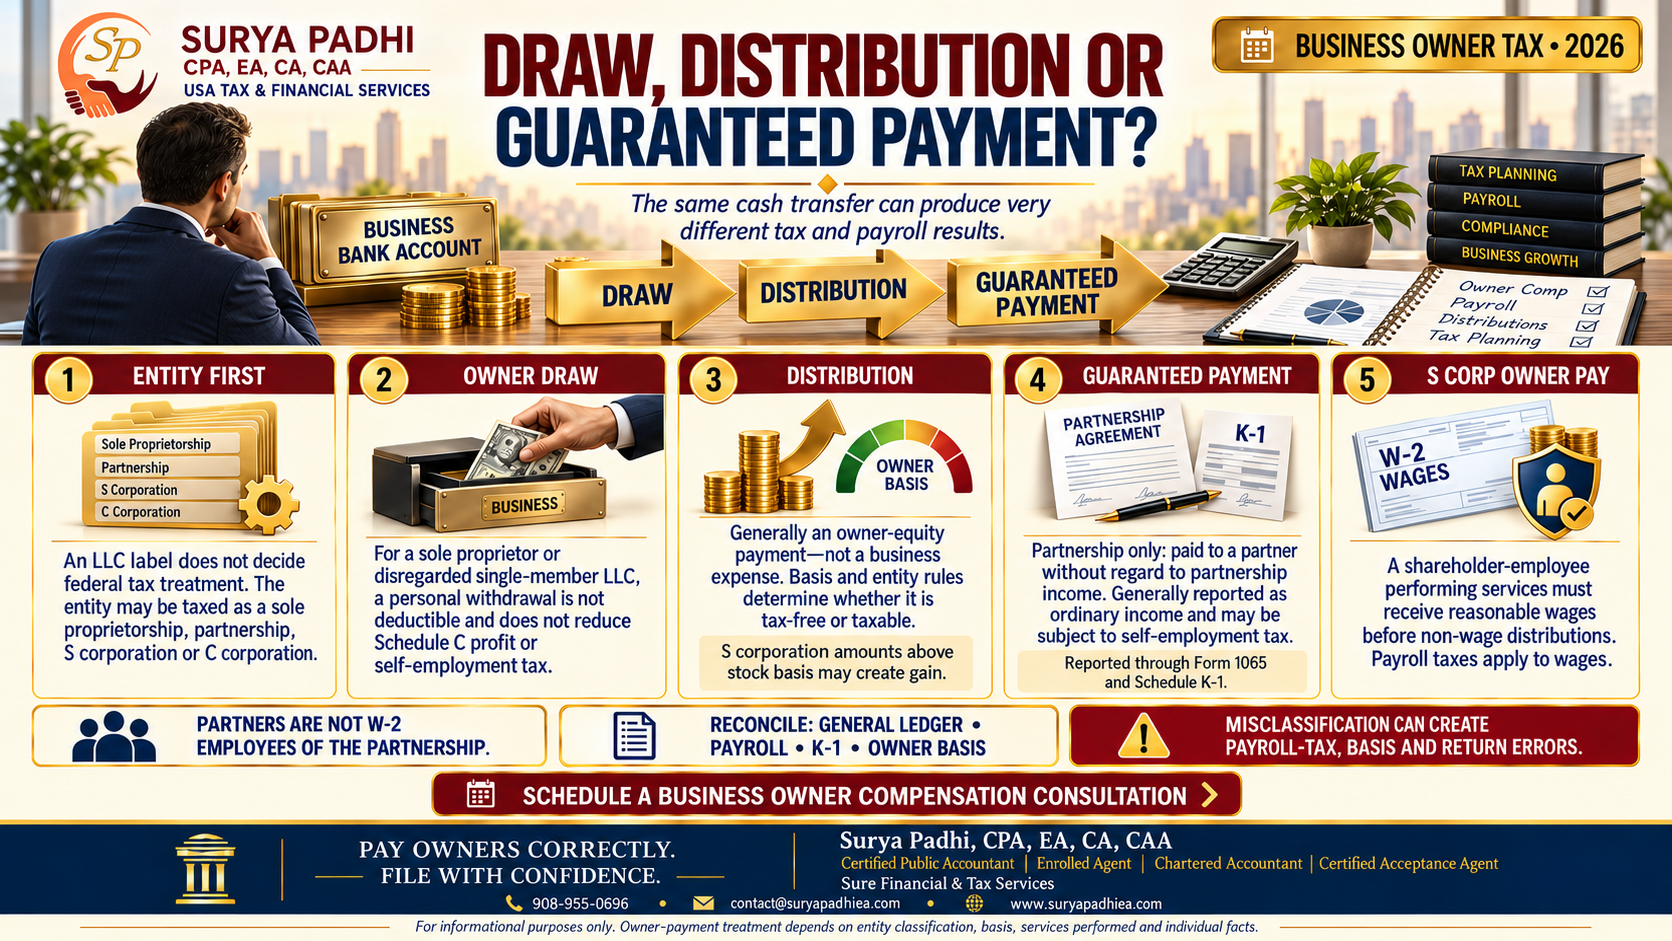
An owner draw is a bookkeeping label for money moved to you, not a tax category. On the return, an S corporation owner is paid W-2 wages plus distributions, a partner is paid guaranteed payments plus distributions, and a single-member LLC owner is taxed on net profit. Your entity type decides which word applies.
7:12. The written version, the figures and the sources are all below.
| S corp pay for your work | W-2 wages | Reasonable compensation before distributions |
|---|---|---|
| S corp cash out | Distribution | Form 7203; K-1 (1120-S) box 16, code D |
| Partner pay for services | Guaranteed payment | Section 707(c); K-1 (1065) box 4 |
| Partner self-employment | Box 14 | Includes guaranteed payments; Section 1402(a) |
| Partner cash out | Distribution | K-1 (1065) box 19 |
| W-2 copies due | Feb 1, 2027 | January 31 is a Sunday |
| Form 1120-S and 1065 due | Mar 15, 2027 | Calendar-year entities |
Three words your accounting software treats as one. The return treats them as three different things, and your entity type decides which one you have.
If you have ever opened your books in January and found twelve months of “Owner Draw” in the equity section, you have met the problem this article is about. Owner draw vs distribution vs guaranteed payment sounds like three names for one thing: money you took out of the business. On the tax return they are three different things, and which one applies depends on how your business is taxed.
Your accounting software lets you name an account anything. The IRS does not read account names. It reads forms: a W-2, a Schedule K-1, a Schedule C. This guide walks through each word, shows where it lands on the return, and gives you a cleanup you can finish before the January and March deadlines.
Key takeaways
- An owner draw is a bookkeeping label for money moved to you. It is not income, not a deduction and not payroll by itself.
- S corporation owners are paid in W-2 wages first and distributions second. Distributions are tax-free only up to stock basis.
- Partners and multi-member LLC members are paid through guaranteed payments and distributions, never a W-2.
- Single-member LLC owners on Schedule C are taxed on net profit, so a draw changes nothing on the return.
Owner draw: a label, not a tax event
An owner draw is money moved from the business account to the owner. That is all it is. It is not income by itself, because the owners of pass-through businesses are taxed on the profit the business earns whether or not they take any of it out. It is not a deduction, because the business never deducts a draw. And it is not payroll, because nothing was withheld and no W-2 was issued.
So the useful question is never “how much did I draw?” It is “what was that money, given how my business is taxed?” There are three possible answers, and the entity picks which one is yours.
Where “draw” is actually the right word
For a sole proprietor or a single-member LLC reporting on Schedule C, draw is the correct everyday term. You are taxed on net profit, and what you pull out does not change that number.
S corporations: wages first, then distributions
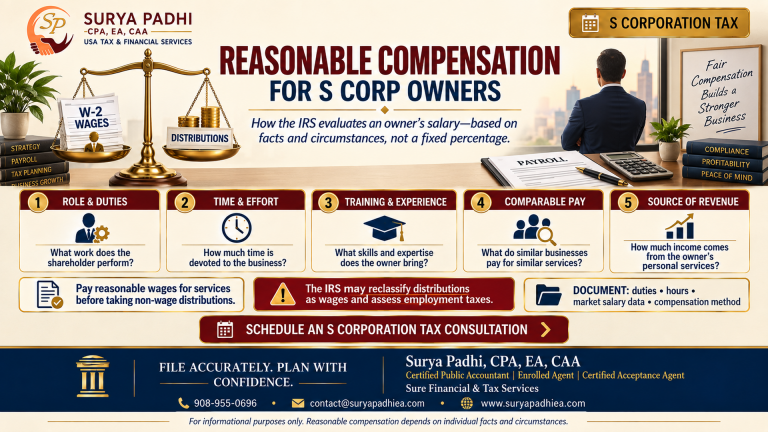
An S corporation owner who works in the business is an employee of it. The IRS expects that owner to receive reasonable compensation for the services performed, through payroll, before taking distributions. Courts have enforced the rule. In Watson v. United States (8th Cir. 2012), an owner who paid himself a very small salary and took the rest as distributions had much of it recharacterized as wages.
Wages
- Run through payroll with withholding and reported on the owner’s W-2.
- Deductible to the S corporation.
- Subject to Social Security and Medicare tax.
Distributions
- Not wages, so not subject to employment taxes.
- Not deductible to the company.
- Applied against the shareholder’s stock basis under Section 1368.
- Taxed as capital gain only to the extent they exceed basis. Basis is tracked on Form 7203, and distributions appear in box 16, code D, of the K-1 (Form 1120-S).
There is no single formula for reasonable pay. The IRS looks at facts such as training and experience, duties, time devoted to the business and what comparable businesses pay for similar services. What matters for your books is the order: wages first, then distributions.
Partnerships and multi-member LLCs: guaranteed payments and distributions
A partnership, or an LLC with more than one member taxed as a partnership, works differently. Partners are not employees of the partnership (Rev. Rul. 69-184), so there is no W-2 for owner pay. The partnership uses two other tools instead.
Guaranteed payments
A guaranteed payment under Section 707(c) is a payment to a partner for services or for the use of capital, determined without regard to partnership income. The partnership deducts it under Section 162(a), and the partner reports it as ordinary income. It appears in box 4 of the K-1 (Form 1065), and it is part of the self-employment earnings reported in box 14.
Distributions
A distribution is a partner taking cash out of their own share. It is reported in box 19 of the K-1, reduces the partner’s basis, and is taxable only to the extent it exceeds basis.
Not a W-2, and not qualified business income
Putting a partner on a W-2 is the wrong form for the relationship. And guaranteed payments are not qualified business income, so they do not count toward the Section 199A deduction.
Owner draw vs distribution vs guaranteed payment, side by side
Here is how the same cash leaving the same bank account is treated under each entity type.
| S corporation | Partnership or multi-member LLC | |
|---|---|---|
| Pay for your work | W-2 wages through payroll | Guaranteed payment under Section 707(c) |
| Deductible to the business? | Wages yes. Distributions no. | Guaranteed payments yes. Distributions no. |
| Payroll tax | Withheld on wages only | None, because partners are not employees |
| Self-employment tax | None on distributions | On guaranteed payments and on your share of income |
| Share of profit | Taxed on the K-1 whether or not paid out | Taxed on the K-1 whether or not paid out |
| Cash taken out | Distribution. Lowers stock basis. | Distribution. Lowers partner basis. |
| Where it shows | W-2 and K-1 box 16, code D | K-1 boxes 4, 14 and 19 |

A single-member LLC that has not elected S corporation status is a disregarded entity. Everything goes on Schedule C, self-employment tax applies to net profit, and an owner draw is simply a transfer, never a deduction. If that LLC has elected S corporation status by filing Form 2553, it follows the S corporation column instead.
The January QuickBooks conversation
Here is a conversation I have most Januaries. A client who owns an S corporation and runs it full time opens the books and finds an equity account called Owner Draw with an entry every month. There has been no payroll, and no W-2 is coming.
What the books show
| Entity | S corporation, owner works full time |
| QuickBooks account | Owner Draw, twelve monthly entries |
| Payroll runs for the owner | None |
| W-2 for the owner | None |
| What the money looks like | Wages for services, not distributions |
| What happens next | Reclassify, then correct payroll with a CPA |
Illustrative scenario. No amounts are shown because the rule does not depend on them.

The owner calls it a draw. The IRS sees an employee-owner who was paid in cash for full-time work with no payroll tax. The fix starts with reclassifying the entries and deciding, with your CPA, how to correct the payroll side before the W-2 deadline. The earlier it is found, the smaller the conversation.
Your January cleanup
- Confirm how the business is taxed: sole proprietor, partnership or S corporation. The filed return or the election letter tells you.
- Export every owner transfer for the year and sort each one into wages, guaranteed payment, distribution or loan.
- Rename or split the accounts so the books say what happened. Owner pay belongs in payroll or guaranteed payments, not in Owner Draw.
- For S corporation owners, check that wages are reasonable for the work and that distributions stay within basis.
- Send the clean books to your preparer ahead of the dates below.

- Thursday, December 31, 2026: last day to run payroll so wages count in 2026.
- Monday, February 1, 2027: W-2 copies due. January 31 falls on a Sunday, so the deadline moves a day.
- Monday, March 15, 2027: Form 1120-S and Form 1065 due for calendar-year entities, with K-1s.
Frequently asked questions
Is an owner draw the same as a distribution?
No. A draw is a bookkeeping label for money moved to the owner. A distribution is a specific tax result for an S corporation shareholder or a partner, and it reduces basis. A sole proprietor’s draw is not a distribution at all, because a sole proprietorship has no shareholders or partners to distribute to.
Can I pay myself only distributions from my S corporation?
Not safely. An S corporation owner who performs services is expected to receive reasonable compensation through payroll before distributions, and the IRS can recharacterize distributions as wages when that does not happen.
What is a guaranteed payment to a partner?
A guaranteed payment is a payment to a partner for services or for the use of capital, determined without regard to partnership income, under Section 707(c). The partnership deducts it, the partner reports it as ordinary income, and it appears in box 4 of the K-1 (Form 1065).
Do I pay self-employment tax on a guaranteed payment?
Generally yes. Guaranteed payments for services are included in a partner’s net earnings from self-employment under Section 1402(a), and they are part of the amount reported in box 14 of the K-1.
Want a second look at how your books label owner pay?
Bring your year-end books and we will sort every owner transfer into wages, guaranteed payments and distributions before the deadlines.
This article is general tax education and does not constitute individualized tax, legal or financial advice. Figures are stated for the tax year shown and are subject to IRS adjustment. Consult a qualified professional about your own facts.