If you never file, the IRS can prepare a return for you under section 6020(b), built only from income reported by employers, banks and brokers. It generally leaves out dependents, itemized deductions, credits and basis, so the tax is usually too high. Filing your own signed return is the way to replace it.
7:15. The written version, the figures and the sources are all below.
| Stalled cases | 38,824 | High-income nonfiler cases in first-notice status at June 30, 2025, as reported by TIGTA. |
|---|---|---|
| Potential assessments | About $15.7B | As reported by TIGTA for those cases. |
| Notice windows | 30 days, then 90 | 30-day letter first, then the notice of deficiency. 150 days outside the United States. |
| Penalty rates | 5% and 0.5% | Failure to file, and failure to pay, per month. Each is capped at 25%. |
| Refund window | 3 years | From the return due date, to claim withholding or estimated tax. |
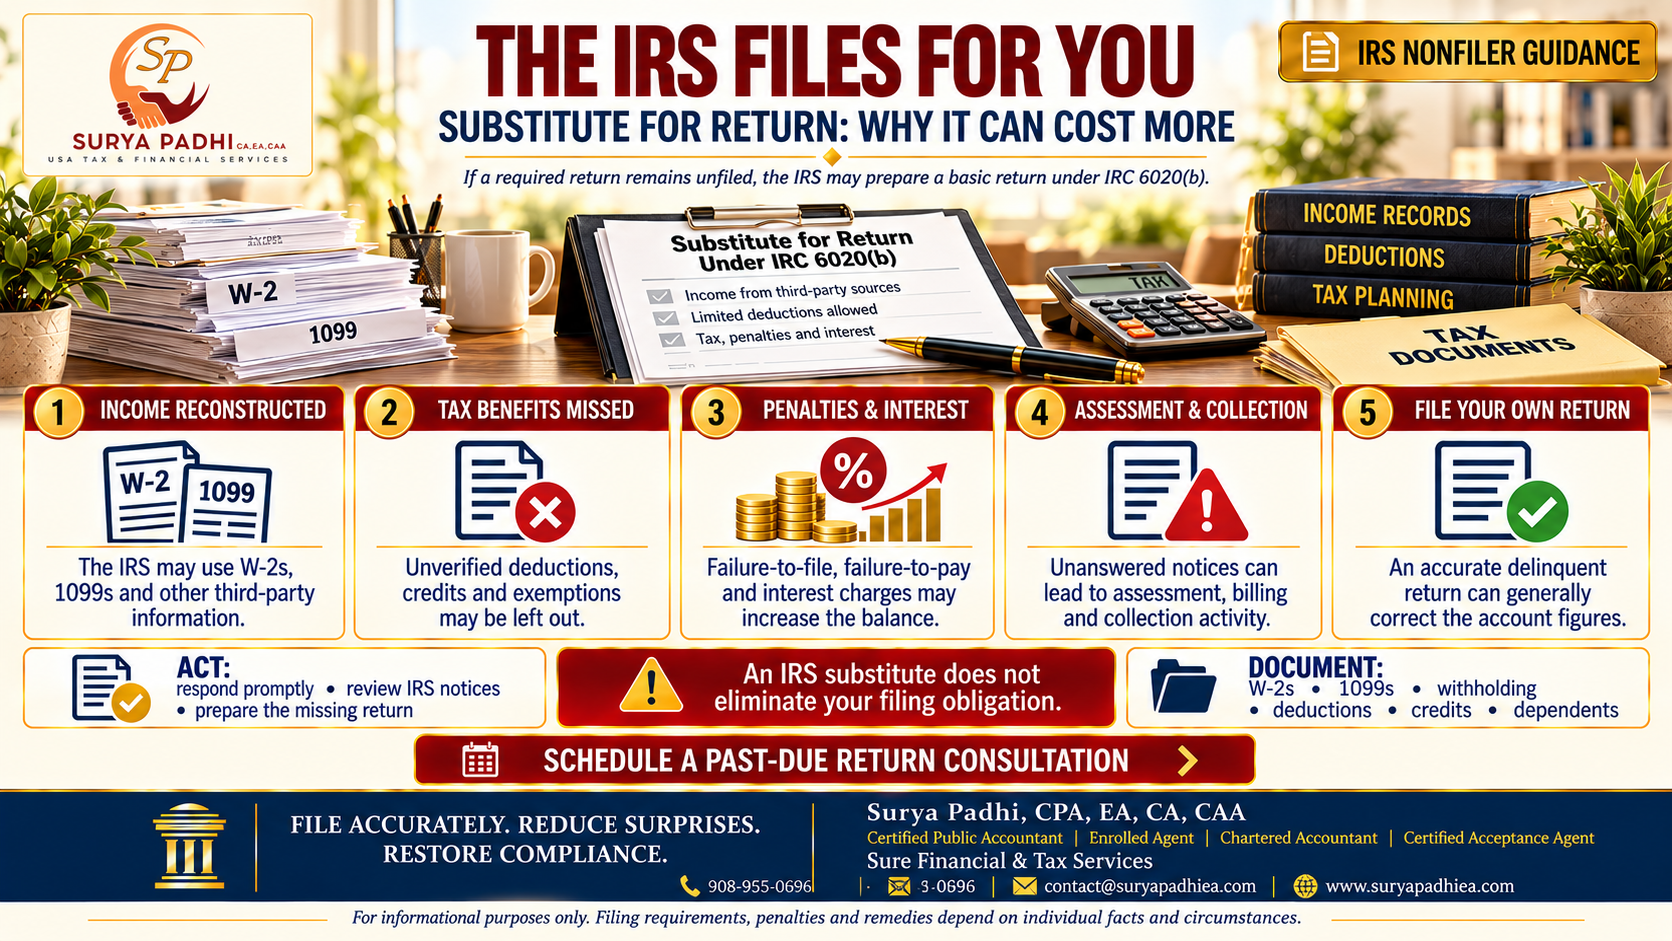
Under section 6020(b) the IRS can write your return from what employers, banks and brokers reported. It leaves out most of what lowers your tax.
Not filing a tax return does not make the IRS stop. When a required return is missing, Internal Revenue Code section 6020(b) lets the IRS make one itself, from its own knowledge and the information it can obtain. That return is called a substitute for return, or SFR, and it is built from the forms that employers, banks and brokers sent in. It does not know your expenses, your dependents or what you paid for the stock you sold.
The timing matters. A report from the Treasury Inspector General for Tax Administration, released on September 4, 2026, describes thousands of high-income nonfiler cases that sat stalled for about two years before the IRS moved them forward in March 2026. This post explains how an SFR is built, which notices come before it, how the two statute clocks work, and how a real return replaces the IRS’s version.
Key takeaways
- An SFR is a return the IRS prepares for you under section 6020(b) when you fail to file. It is built only from third-party reports.
- It generally leaves out dependents, itemized deductions, credits and, where a report carries none, your basis. That is why the tax on it is usually too high.
- You get a 30-day letter and then a 90-day notice of deficiency, or 150 days if you are outside the United States. The 90 days is a firm deadline.
- Filing your own signed return is the strongest answer, and for refunds of withholding or estimated tax you generally have only 3 years from the due date.
What a substitute for return is
Section 6020(b)(1) says that when a person fails to make a required return, the IRS shall make the return from its own knowledge and from such information as it can obtain through testimony or otherwise. Section 6020(b)(2) adds that a return made this way is prima facie good and sufficient for all legal purposes. In plain terms, once the IRS builds one, the law treats it as a valid return until someone shows otherwise.
Do not confuse it with section 6020(a), where a person who did not file agrees to disclose the information needed and signs a return the IRS prepared. That is cooperation. An SFR is what the IRS does when there is none.
Your return versus theirs
Your return reports what is true: your income, your expenses, your basis and everything you qualify to claim. An SFR reports what third parties told the IRS, and nothing else.
Why this is in the news now
TIGTA’s report, titled “Agencywide Coordination Could Enhance the IRS’s Approach to Nonfilers,” is dated August 31, 2026 and was released on September 4, 2026. It found 38,824 high-priority nonfiler cases, involving 33,653 taxpayers, sitting in first-notice status as of June 30, 2025. TIGTA reported about $15.7 billion in potential assessments tied to those cases. The IRS advanced the cases in March 2026, and it agreed with all six of TIGTA’s recommendations, which include a comprehensive agencywide strategy for nonfilers.
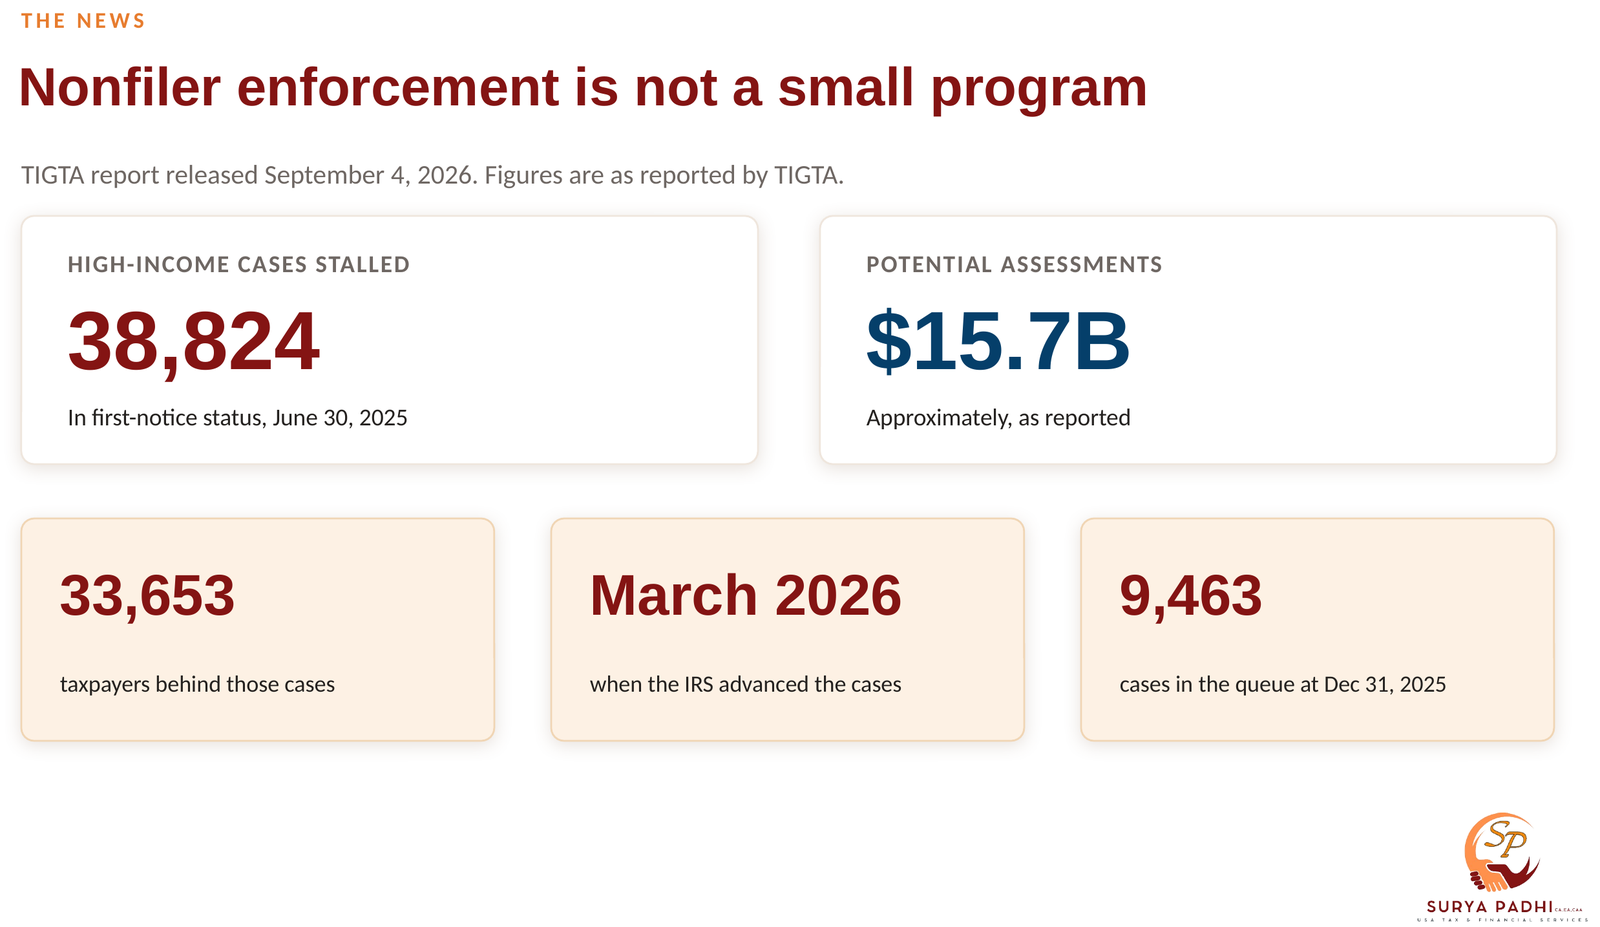
One detail is easy to misread. The 9,463 figure that appears in coverage of the report is the number of nonfiler cases waiting in the queue at December 31, 2025, down from 10,969. It is not the first-notice count. The takeaway is simple: enforcement against high-income nonfilers was delayed, the IRS has now moved on it, and unfiled years are a bigger risk than they were last year.
How the IRS builds its version
The IRS starts with the information returns filed under your Social Security number: Forms W-2, the 1099 series and similar reports. The National Taxpayer Advocate has described the program as treating you as single, or married filing separately where there is evidence you are married, with only a standard deduction. It does not apply itemized deductions or credits, even when the IRS already holds forms such as the 1098 that would support them.
| Item | IRS substitute return | Your real return |
|---|---|---|
| Filing status | Single, or married filing separately | The status you qualify for |
| Dependents | None | Everyone you can claim |
| Deductions | Standard deduction only | Standard or itemized, whichever is larger |
| Credits | None considered | Every credit you qualify for |
| Stock sales | Proceeds, often without basis | Proceeds less your basis |
The IRS says the same thing in its own words: a substitute return might not give you credit for deductions and exemptions you may be entitled to receive. Business owners feel it most, because gross receipts reported on a 1099 are taxed with none of the expenses that produced them. Investors feel it when a report shows proceeds without a basis, since there may be nothing for the IRS to subtract.
Reported income is not your income
An SFR taxes what was reported to the IRS. Only a return you prepare and sign can show what you actually earned, spent and paid.
The notices, in order
An SFR rarely arrives without warning. The sequence is set, and each step has a response window.
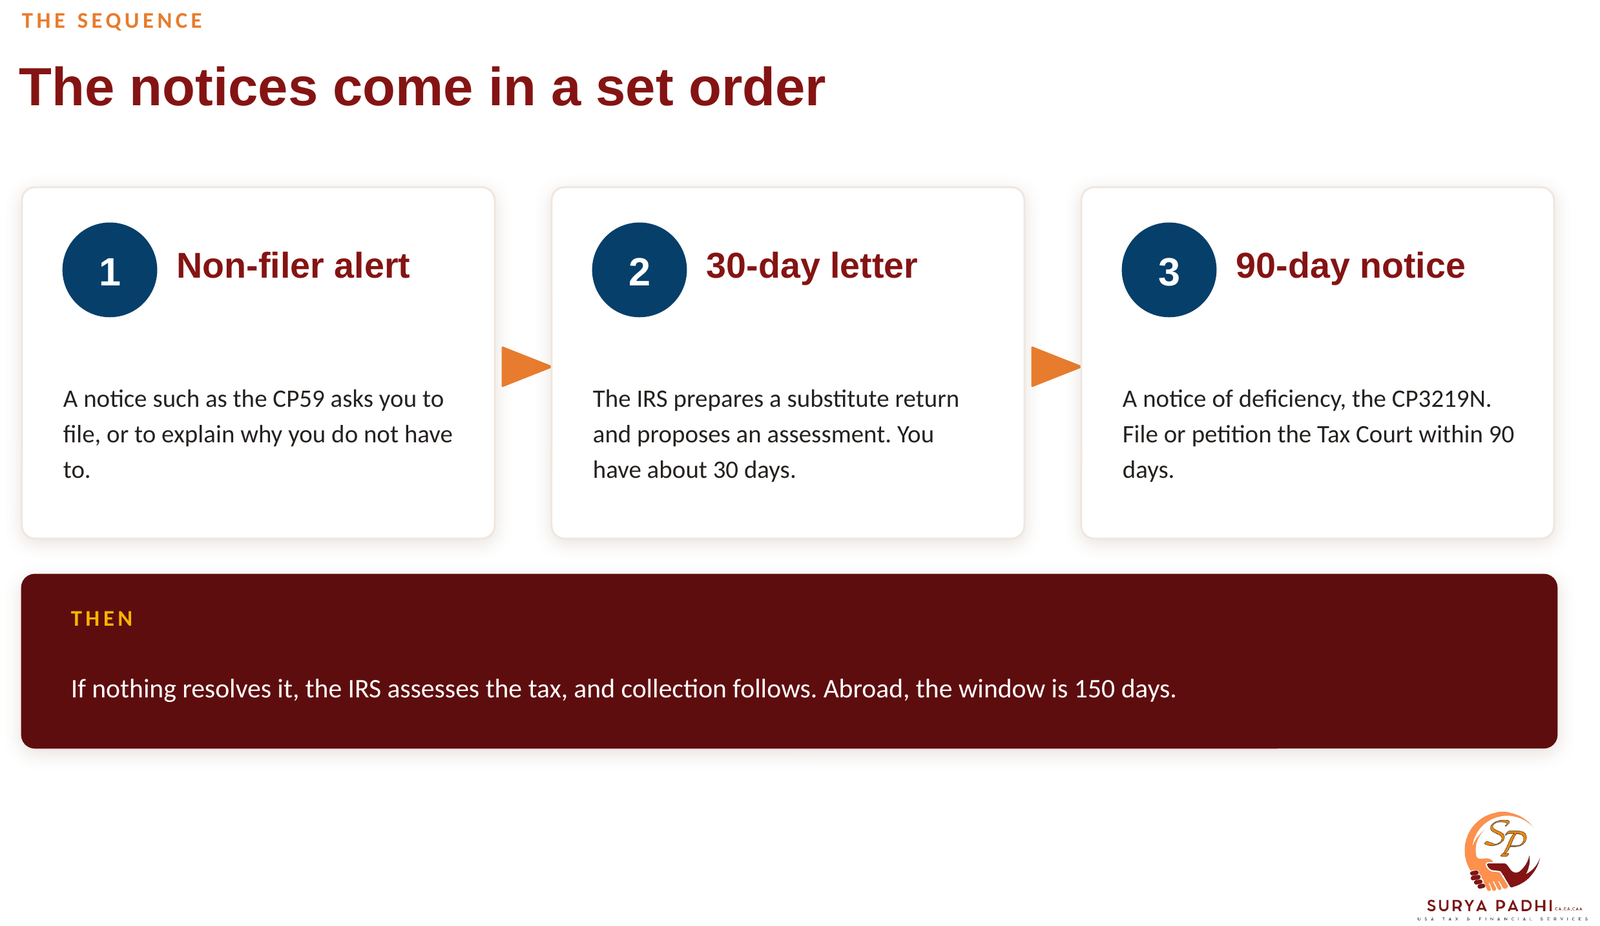
- A non-filer alert, such as the CP59, asks you to file your signed return or explain why you do not need to. The IRS provides Form 15103 for the explanation.
- If nothing resolves it, the IRS prepares a substitute return and sends a 30-day letter proposing the assessment, with the tax, penalties and interest it computed. This is Letter 2566.
- Next comes the statutory notice of deficiency, the CP3219N. You have 90 days from the date of the notice to file your return or petition the United States Tax Court, or 150 days if you are outside the United States.
- If the window closes with no resolution, the IRS assesses the tax, and collection actions such as liens and levies can follow.
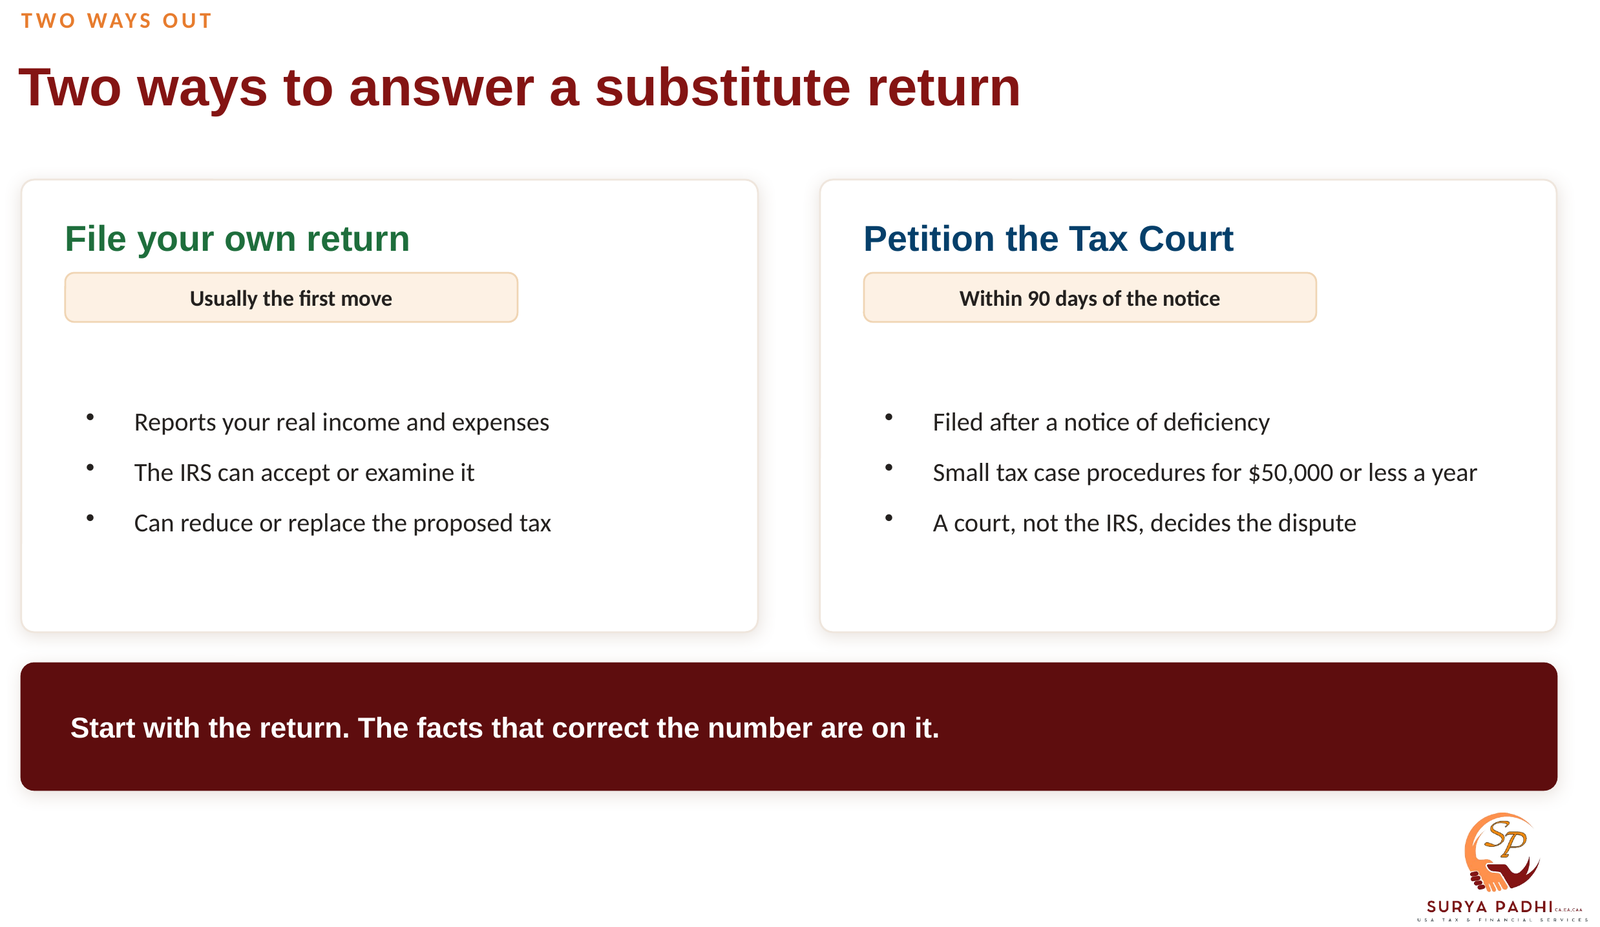
The Tax Court offers simplified procedures for disputes of $50,000 or less per tax year. A notice you did not open is still a notice with a date on it, so read the date on every IRS envelope.
What it costs to wait
The proposed tax is only part of the bill. The failure-to-file penalty is 5% of the tax due for each month or partial month the return is late, to a maximum of 25%. The failure-to-pay penalty is 0.5% a month, also to a maximum of 25%. When both apply, the failure-to-file penalty is reduced by the failure-to-pay amount, so the two together run at 5% a month for the first five months. The failure-to-pay penalty then keeps running, and the IRS charges interest on penalties as well as on tax.
Five months late, in illustrative numbers
| Tax due on the unfiled return | $10,000 |
| Combined penalty rate, per month | 5% |
| Months late | 5 |
| Penalties after five months, before interest | $2,500 |
Illustrative only, not a client result. It assumes the full amount stays unpaid and ignores interest and any minimum penalty.
Penalties are calculated on the tax shown on the return. Because an SFR often overstates that tax, the penalties on it are overstated too. Correcting the return corrects the base they are built on.
The two clocks
Two statutes of limitation run in opposite directions here. The assessment clock limits how long the IRS has to assess tax. Section 6501(c)(3) says that when no return was filed, the tax may be assessed at any time, and an SFR does not count as your return for that purpose. The clock starts when you file a valid signed return.
The collection clock works differently. The IRS generally has 10 years to collect from the date of assessment under section 6502, and an assessment based on an SFR starts that period. So an SFR can leave you with a collectible balance on an unfiled year whose assessment clock never started. That is another reason to file.
Filing starts the clock the IRS cannot start for you
Only your signed return starts the assessment period. Leaving a year unfiled keeps it open indefinitely.
Replacing their return with yours
The IRS says it plainly: if it files a substitute return, it is still in your best interest to file your own return to take advantage of the exemptions, credits and deductions you are entitled to. The IRS can accept your return or examine it and adjust it if warranted, and the National Taxpayer Advocate notes that an original return can reduce or eliminate the proposed liability.
A stock sale, in illustrative numbers
| Proceeds shown on the brokerage report | $60,000 |
| Your actual basis, from your records | $52,000 |
| Gain if the IRS has no basis to subtract | $60,000 |
| Gain on your real return | $8,000 |
| Income taxed that never existed | $52,000 |
Illustrative only, not a client result. It assumes the report carries no basis for the sale.
Basis is often the number that moves most, and records for it get harder to find as the years pass. If the notice deadline is not close, take the time to collect it.
What to do now
- Read every IRS notice and find the response date. Do not let it pass.
- Gather income forms for each unfiled year, and pull your IRS wage and income transcripts to see what the IRS has.
- Rebuild each year on that year’s forms and rules, with basis, deductions and credits.
- File signed returns for every year and keep proof the IRS received them.
- Plan the balance. If tax is owed, ask about a payment plan, because the failure-to-pay penalty runs at a lower rate during an approved plan.
Refunds are the quiet casualty of waiting. To claim a refund of withholding or estimated tax, you generally must file within 3 years of the return due date, and the IRS says you cannot get a credit or refund after that unless an exception applies.
| Date | What to do |
|---|---|
| Right away | Read every notice and note its response date |
| October 15, 2026 | Extended 2025 returns are due, if you filed an extension |
| Any time | Penalties and interest keep building until you file and pay |
| April 15, 2027 | 2026 return due. A good date to be fully caught up |
Frequently asked questions
What is an IRS substitute for return?
It is a return the IRS prepares for you under section 6020(b) when you do not file. It is built from income reported by employers, banks and brokers, and it generally leaves out deductions, credits and dependents.
How long do I have to respond to a notice of deficiency?
You have 90 days from the date on the notice to file your return or petition the United States Tax Court, or 150 days if you are outside the United States.
Does an IRS substitute return start the statute of limitations?
Not the assessment period. Where no return was filed, tax may be assessed at any time, and your own signed return starts that clock. An assessment based on the SFR does start the 10-year collection period.
Can I file my own return after the IRS files a substitute return?
Yes. The IRS says it is in your best interest to do so. The IRS can accept your return or examine it, and a correct original return can reduce or replace the proposed liability.
Behind on filing? Let’s get you current
Sure Financial and Tax Services can gather your records, prepare each unfiled year and help you respond to the IRS.
This article is general tax education and does not constitute individualized tax, legal or financial advice. Figures are stated for the tax year shown and are subject to IRS adjustment. Consult a qualified professional about your own facts.